Investing in Germany as an Expat: Finding the Right Strategy for You
Moving to Germany often means starting to think differently about your finances. You may have built savings in your home country, started earning a higher salary, or simply reached a point where leaving your money in a bank account no longer feels like the best long-term solution.
But investing as an expat in Germany raises an important question:
Where should you invest your money, and what is the right strategy for you?
There is no single answer.
ETFs are often presented as the obvious solution, but they are certainly not the only option. Depending on your objectives, timeframe, risk tolerance, tax situation and plans for the future, different investments may make sense and in many cases, a combination of different investments may be appropriate.
The goal should not be to find the “best investment”.
It should be to build an efficient investment strategy that matches your personal situation and financial goals.
What Can You Invest In?
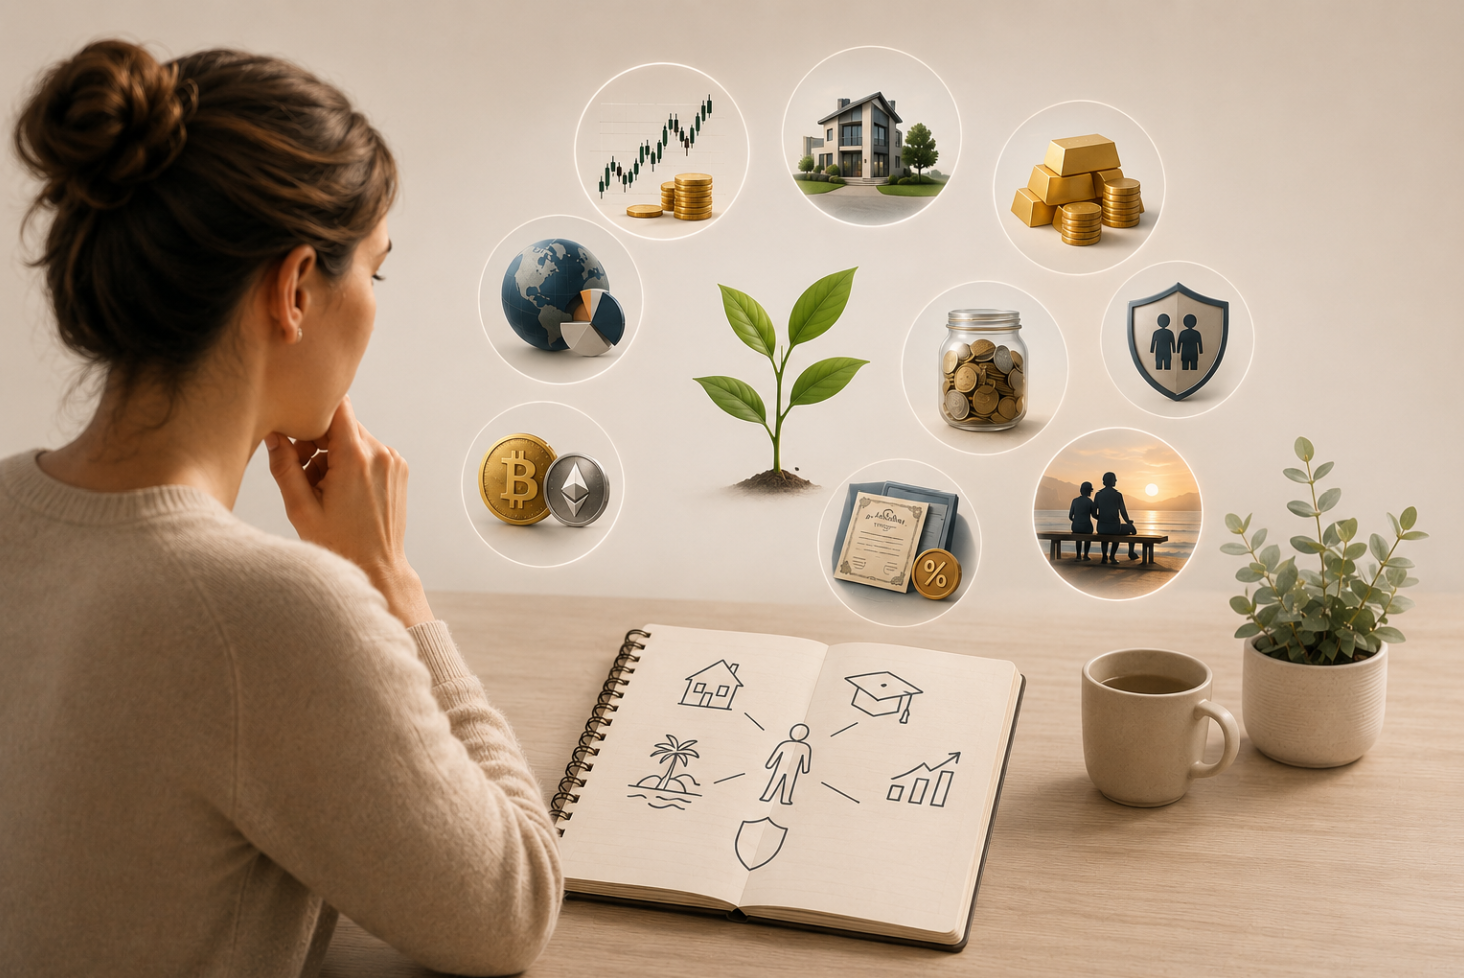
There are many investment options available in Germany. Depending on your circumstances, you might consider:
- ETFs & investment funds : offer diversification and can be an efficient way to invest in financial markets. However, levels of diversification and risk can vary considerably.
- Individual shares : provide direct exposure to individual companies and the potential for higher returns, but also involve greater concentration, volatility and risk.
- Cryptocurrencies : offer significant growth potential but are highly volatile and carry substantially higher risks than many traditional investments.
- Bonds & fixed-income investments : can provide more predictable income and help reduce portfolio volatility, although returns and risks depend on the type of investment and the issuer.
- Savings & term deposits : generally lower risk and useful for emergency funds and short-term goals, but their potential for long-term growth may be limited.
- Real estate : can provide rental income and potential long-term capital appreciation, but requires significant capital, involves ongoing costs and is less liquid than many financial investments.
- Pension solutions : including occupational and private pensions, can play an important role in retirement planning and may offer tax or other advantages, but access to the money is generally restricted until a specific age.
- Life insurance & investment-linked insurance : can combine investment with insurance or long-term financial planning. May offer tax or other advantages.
- Gold, silver & other commodities : can provide diversification and may help protect against certain risks, but generally do not generate income and can be volatile. In Germany, the tax treatment of physical gold and silver can also be interesting to consider.
And these are not the only possibilities.
The important point is that each investment has its own advantages, disadvantages, costs, risks and tax implications.
So how do you know what is right for you?
Start With Your Objectives
Before choosing an investment, ask yourself:
What am I trying to achieve with this money?
Are you investing for:
- a future property purchase?
- your children’s education?
- retirement?
- financial independence?
- long-term wealth creation?
- a specific future expense?
Having clear objectives helps you determine how much risk you can take, how long you can invest and how much flexibility you need.
It can also help you stay disciplined and consistent with your savings.
Your Time Horizon Matters
The next question is:
When will you need the money?
Short term
If you need the money within the next few years, perhaps for a house deposit, a move or another major expense, protecting your capital and keeping your money accessible may be more important than pursuing higher returns.
Medium term
For medium-term goals, you may be able to accept some market fluctuations in exchange for potentially higher returns, depending on how flexible your timeframe is.
Long term
For goals such as retirement or long-term wealth creation, you generally have more time to deal with market fluctuations. This can make growth-oriented investments such as diversified ETFs and funds worth considering.
However, a longer timeframe does not automatically mean taking maximum investment risk.
Your risk tolerance matters too.
An investment strategy only works if you are comfortable enough with the level of risk to stick with it when markets fall.
Don’t Forget About Tax
Investment returns should always be considered after taxes and costs, rather than simply looking at the headline return.
In Germany, investment income such as interest, dividends and certain capital gains is generally subject to capital income taxation. There is also an annual Sparer-Pauschbetrag of €1,000 per person.
Different types of investments can receive different tax treatment.
For expats, there can be an additional layer of complexity if you already own investments in your home country or plan to move away from Germany in the future.
Before selling, transferring or restructuring existing investments, it is therefore important to understand the potential tax consequences.
The Strategy Comes Before the Investment
A common mistake is to start with the question:
“Which ETF should I buy?”
A better starting point is:
“What am I trying to achieve with this money?”
Once you understand your goals, timeframe, risk tolerance and financial situation, you can then determine which investments and solutions may be appropriate.
The best investment strategy is not the one everyone else is using. It is the one that is designed around you.
Need Help With Your Investment Strategy?
Not sure which investments are right for you or how to structure them?
We can help you build a personalised investment strategy based on your goals, timeframe, risk tolerance and financial situation.
Let’s find the right strategy for you.